By Simon Gedz, Local Realtor
Charles Rutenberg Realty · 30+ years of South Florida market expertise · Published October 21, 2026
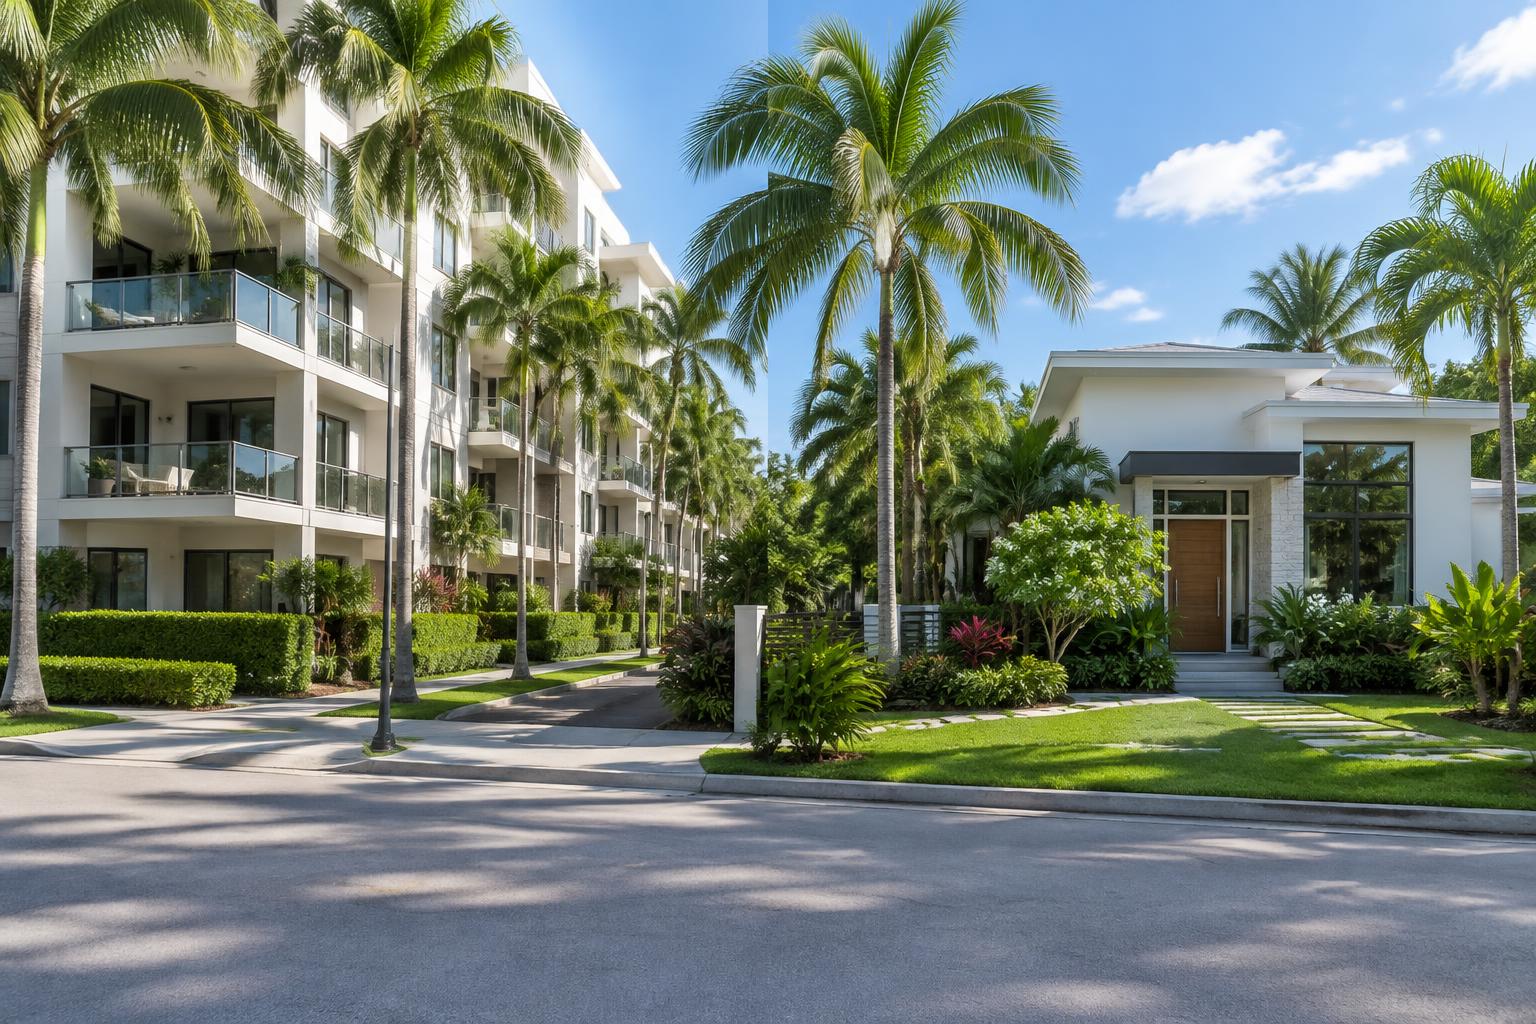
A buyer walks into my office, looks at a condo listing, winces at the $1,200 monthly association fee, and says, “I’d rather own a house and avoid that. I don't want to pay someone else for maintenance.”
I’ve been a Realtor here in South Florida since 1995, and I have heard that exact sentence hundreds of times. It is a natural reaction, but it is also a trap. When you look at a condo fee, you are looking at a line item that is fully transparent. When you look at a single-family home, those same costs are often hidden, variable, or ignored until the day something breaks.
The comparison is never Condo Fee versus Zero. It is always Total Ownership Cost versus Total Ownership Cost. Let’s break down the reality of the market as it stands right now. As of November 2026 on our site, we are tracking 2812 active homes in Fort Lauderdale with a median list price of $750,000. If you are looking at waterfront properties—where 1182 are currently listed—that median jumps to $1,050,000. Whether you choose the condo or the house, the math requires a much deeper dive than just checking the monthly HOA dues.
The Hidden Costs of the Single-Family Home
When you own a house, you are the board of directors, the property manager, and the maintenance crew. You might save on the monthly fee, but you will almost certainly pay that money elsewhere.
First, consider the lawn and landscape. In a condo, your landscaping is covered by the association. In a house, if you don't do it yourself, you are hiring a professional service. In South Florida, where the grass grows year-round, that is a recurring expense that many buyers forget to budget. Then there is the pool. If you buy a waterfront home, you likely have a pool and perhaps a seawall. A seawall inspection and maintenance is a significant, infrequent, but necessary cost that a condo association would handle for you through your reserve fund.
Insurance is the other giant. As of November 2026 on our site, understanding the total carry cost of a home requires looking at windstorm and flood insurance premiums. Florida law dictates specific requirements for building envelopes and hurricane mitigation. Houses generally have higher insurance premiums per square foot than high-rise condos because the condo association carries a master policy that covers the exterior and the structural elements of the building. With a house, the burden is 100% on you.
What the Condo Fee Actually Buys
People look at the condo fee as an expense, but they should look at it as a service contract. A well-managed building is essentially an outsourced property management firm. Your fee is covering:
- Roof and structural integrity of the building.
- Building insurance (which is often cheaper than insuring a standalone home).
- Landscaping, pool maintenance, and common area cleaning.
- Security personnel, which is a major value in high-end Fort Lauderdale neighborhoods.
- Water, sewer, and trash removal, which are often bundled into the fee.
If you are a seasonal resident—someone who spends six months in New York and six months here—a condo offers peace of mind that a house simply cannot match. You lock the door, you leave, and you don’t worry about the roof leaks, the pool pump failing, or the lawn becoming a jungle. For a part-time resident, the "convenience premium" of a condo fee is often the cheapest form of insurance against property neglect.
Evaluating the Math: A Checklist for Buyers
Before you decide which path is right for you, I recommend performing a comparative analysis. Do not just look at the monthly HOA. Use this checklist to verify your actual expenses:
- Review the Reserves: Ask for the latest board meeting minutes and the reserve study. If the association hasn’t been putting money aside, a special assessment for a new roof or balcony restoration is coming. That is a hidden cost waiting to explode.
- Verify the Insurance: Ask the listing agent for the last annual premium for the property. For a house, get a wind mitigation report. This document can save you thousands on your annual premium.
- Check the Homestead Exemption: If this is your primary residence, you are entitled to a homestead exemption. Verify the current tax bill with the Broward County Property Appraiser’s office, not just what is listed on the MLS. Taxes often reset after a sale.
- The Boating Factor: If you are buying a waterfront home for your boat, ensure the dock is permitted and the draft is sufficient for your vessel. Maintaining a dock and lift is a specific house-owner expense that has no condo equivalent.
Independence vs. Community
There is an intangible value to ownership. If you want a garden, a fence for your dog, or the ability to renovate your interior without waiting for architectural review board approval, you need a single-family home. That independence is worth paying for. You are paying for the right to control your environment entirely.
Conversely, if you value community and predictable costs, the condo model is superior. You know exactly what your monthly overhead is. There are fewer "surprise" repairs that hit your checking account all at once. If the roof needs repair in a condo, the association board handles the bidding, the contract, and the project management. In a house, you are the project manager.
Making the Decision
When I talk to clients who are moving from New York to South Florida, they are often shocked by the cost of property taxes and insurance here. It is a different ecosystem than what they are used to. I tell them to build a realistic annual budget for either option. When you look at the total cost of ownership—taxes, insurance, maintenance, landscaping, repairs, and fees—the gap between a condo and a house is often much smaller than the sticker price suggests.
It ultimately comes down to your tolerance for maintenance. Do you want to spend your Saturdays in Florida managing contractors, or do you want to spend them on the water? If you find yourself leaning toward the water, you should also look at our waterfront neighborhood guide to see which areas offer the best balance of lifestyle and investment security for your specific needs.
If you are currently trying to determine which type of property aligns best with your financial goals, do not try to guess the maintenance costs. Use my experience to help you run the numbers. We can compare the cost of a high-rise in Galt Ocean Mile against a single-family home in Victoria Park or Rio Vista. Whether you are looking to sell your current property or invest in your first piece of Florida paradise, you should be working with data, not just assumptions.
For a deeper dive into the market or to get a custom analysis of a specific building or neighborhood, you can always check my client reviews to see how I have helped others navigate this process.
Next step: Call me directly at 954-562-1798. We can discuss your specific lifestyle requirements, your budget, and whether a condo or a single-family home in Fort Lauderdale is the smarter move for your long-term portfolio. Let’s sit down and run the numbers properly.