By Simon Gedz, Local Realtor
Charles Rutenberg Realty · 30+ years of South Florida market expertise · Published October 21, 2026
Originally published in the S.G. Trust Team Newsletter.
This is one of the most common questions I hear from buyers moving to South Florida. Since 1995, I have guided clients through the unique landscape of our regional real estate market, and I can tell you that insurance is the single biggest variable in your annual budget.
Generic answers are not just unhelpful here; they are dangerous. In South Florida, your insurance premium is not based on a broad regional calculation. It is tethered to the specific DNA of the structure you intend to buy.
Insurance Is Property-Specific
Two homes with the same purchase price may have insurance profiles that are lightyears apart. You might be looking at two properties in Fort Lauderdale homes for sale priced at $750,000, which is the current median list price as of November 2026 on our site. However, one house might be a 1950s block construction home with a newer metal roof, while the other could be an older frame home with an outdated electrical panel.
The differences extend to elevation, proximity to the coast, and your wind mitigation report. If you are browsing our 1,182 waterfront properties, which have a median price of $1,050,000 as of November 2026 on our site, the flood insurance component becomes significantly more complex. Factors like base flood elevation versus your finished floor elevation can lead to massive swings in your annual carrying costs.
Start Early in Your Due Diligence
Do not wait until you are deep into the transaction to start investigating insurance. I tell every client that the moment we have a property under consideration, insurance needs to be part of your due diligence checklist.
When you start your search, use our waterfront and boating tools to narrow down your geography, but do not stop there. Once you find a specific neighborhood that appeals to you, check out my Fort Lauderdale waterfront neighborhood comparison to understand which areas carry higher insurance risk profiles. You want to have a preliminary conversation with an insurance agent long before your inspection period ends.
Don't Use Online Estimates as Guarantees
You will find many generic calculators online. They can be useful for preliminary planning, but they are not guarantees. An online estimator does not know the age of your plumbing, the type of wiring (Knob and Tube vs. Copper vs. Aluminum), or the condition of your roof.
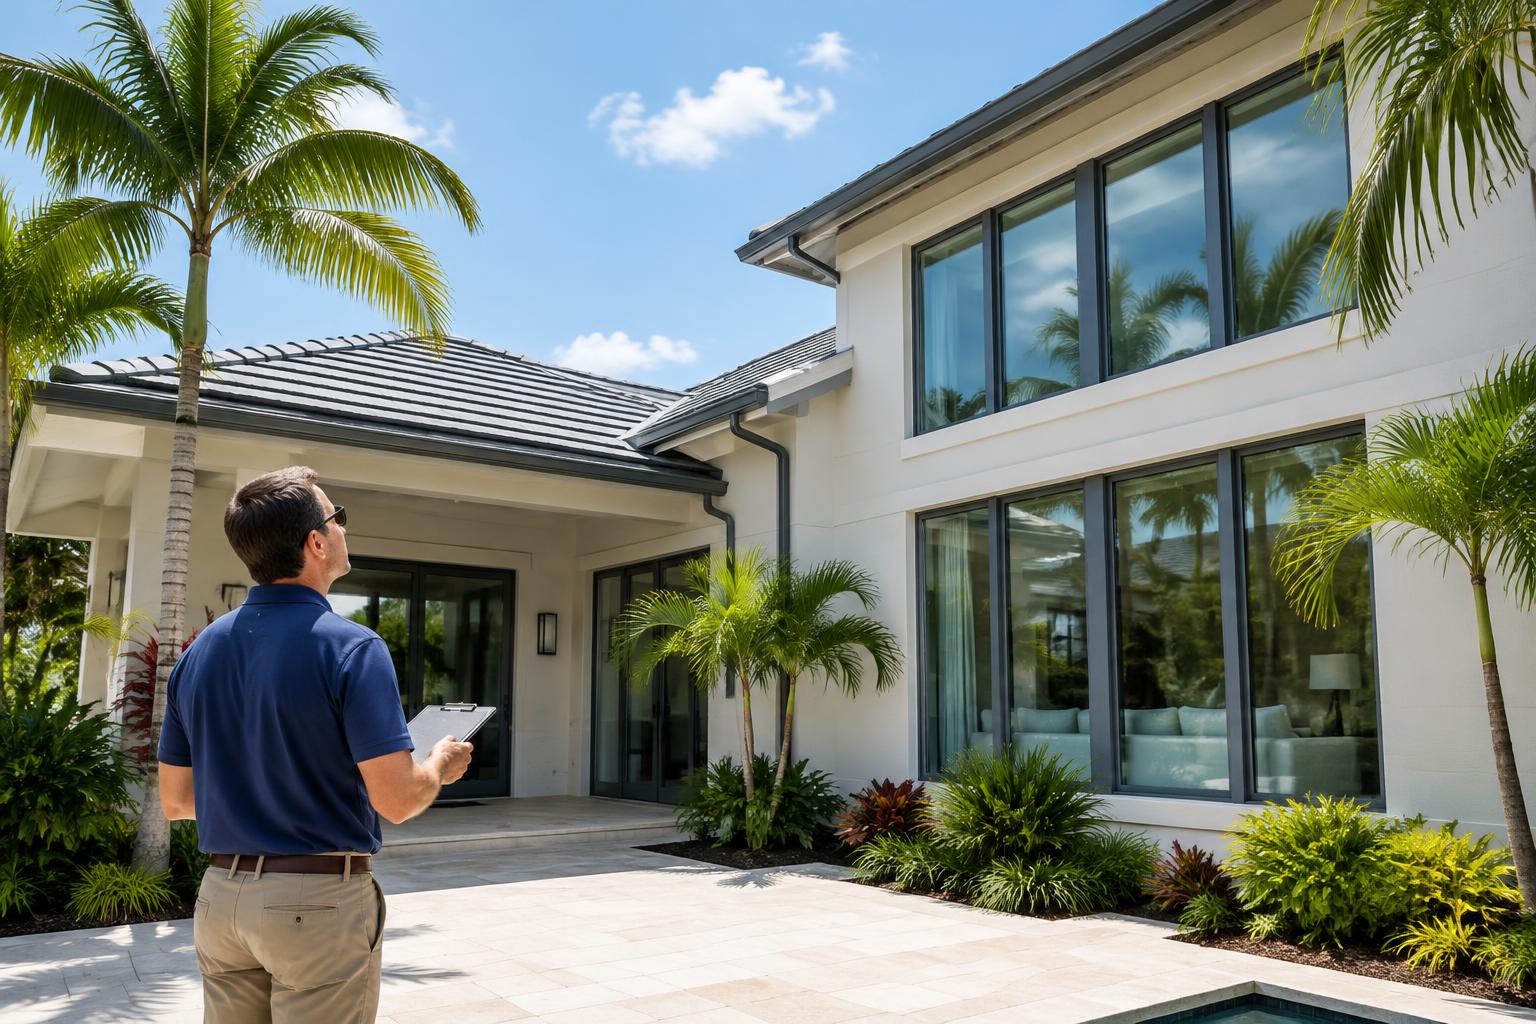
In Florida, insurance companies are heavily focused on "4-Point Inspections," which look at:
- Heating and Air Conditioning
- Electrical Wiring and Panels
- Plumbing Connections and Fixtures
- Roof Condition
If any of these components are near the end of their useful life, the insurance company may decline coverage entirely or require a massive premium increase. Relying on an internet quote for a "hypothetical" house will leave you unprepared when a real quote comes back significantly higher due to a failing roof or an outdated electrical panel.
Understand What You Are Comparing
When I sit down with clients to review their potential budget, I urge them not to look only at the premium. You must look at the "fine print" of your policy.
- Deductibles: Are you choosing a percentage deductible (e.g., 2% for wind/hail) or a flat dollar amount? A lower premium often hides a much higher deductible that could cost you tens of thousands of dollars in the event of a storm.
- Replacement Cost vs. Actual Cash Value: Never settle for Actual Cash Value. You want a policy that covers the cost to rebuild your home to current code, not just the depreciated value of the structure.
- Exclusions: Many Florida policies exclude certain types of water damage or require separate policies for windstorm and flood.
If you are new to the area, I highly recommend reading my guide on moving from New York to South Florida for a broader look at how our costs of living differ from the Northeast.
Use an Appropriate Insurance Professional
As your realtor, I can help you identify that insurance is an issue and suggest reputable professionals who specialize in the Florida market. However, the final analysis must come from a licensed insurance broker.
They will need the Wind Mitigation Report and the 4-Point Inspection to provide an accurate quote. If the seller does not provide these, you will need to pay for them during your due diligence period. Trust me, it is the best money you will spend. I have saved clients from bad investments by flagging insurance issues early; nothing ruins a home purchase quite like finding out after the closing that the home is uninsurable or that the premium is double what you budgeted.
Also, be sure to verify your eligibility for the Florida Homestead Exemption. It won't lower your insurance, but it provides significant tax savings that can help offset your carrying costs. You can find more information in my Florida homestead exemption guide.
Know Before You Commit
The purpose of this advice is not to make Florida ownership sound intimidating. It is to eliminate surprises. I want my clients to walk into their new homes with their eyes wide open, feeling confident about the math behind their purchase. Whether you are looking for a compact canal home or something fitting for a larger vessel—which you can research using my homes by boat size guide—ensure that the home fits your budget after insurance and taxes are calculated.
Don't go it alone. You can see what my past clients have to say about how my team handles these details, and if you are ready to put your own property on the market, learn more about selling with Simon.
If you are looking for a specific type of property, please remember that we have 2,812 active homes in our database as of November 2026 on our site. I have seen the market go through every cycle since 1995, and I am here to help you navigate it safely.
Next Step: If you have questions about a specific neighborhood or need help finding an insurance professional who understands the local landscape, let’s talk. Call me at 954-562-1798.